



How many times have we heard that oil prices and inflation are increasing the cost of governments’ borrowing? How many times have we heard that this is because of events in the Strait of Hormuz?
You may be surprised, or not, to discover that they are not telling you the full story.
Oil prices and inflation are proximate causes, economist Peter C. Earle says. The real problem began several years ago during the so-called covid pandemic.
Let’s not lose touch…Your Government and Big Tech are actively trying to censor the information reported by The Exposé to serve their own needs. Subscribe to our emails now to make sure you receive the latest uncensored news in your inbox…
Bond Markets Are Losing Patience – And Putting Governments on Notice
By Peter C. Earle, as published by The Daily Economy on 3 September 2026
Something unusual is happening in global bond markets, and it is more consequential than the usual swings in yields. Government borrowing costs are rising across much of the developed world. The US 10-year Treasury is approaching 5 per cent and the 30-year Treasury yield is at levels not seen since 2007. “Meltdown” is too dramatic a word, but the bond market is clearly sending a message. Bond prices fall when investors demand higher yields, and global investors clearly want to be paid more for lending money to governments carrying large debts, running persistent deficits and still contending with above-target inflation.
Japan is perhaps the most striking case. Its 10-year government bond yield has moved through 3 per cent after spending most of a generation near zero, and its 30-year borrowing cost has risen above 4 per cent – a multi-decade high. Australia’s 10-year recently reached 5.16 per cent. Germany’s 10-year Bund has been trading around 3.3 per cent, with the 30-year above 3.8 per cent. Britain, France and other developed economies are seeing versions of the same thing. The particulars differ from country to country, but the direction does not.
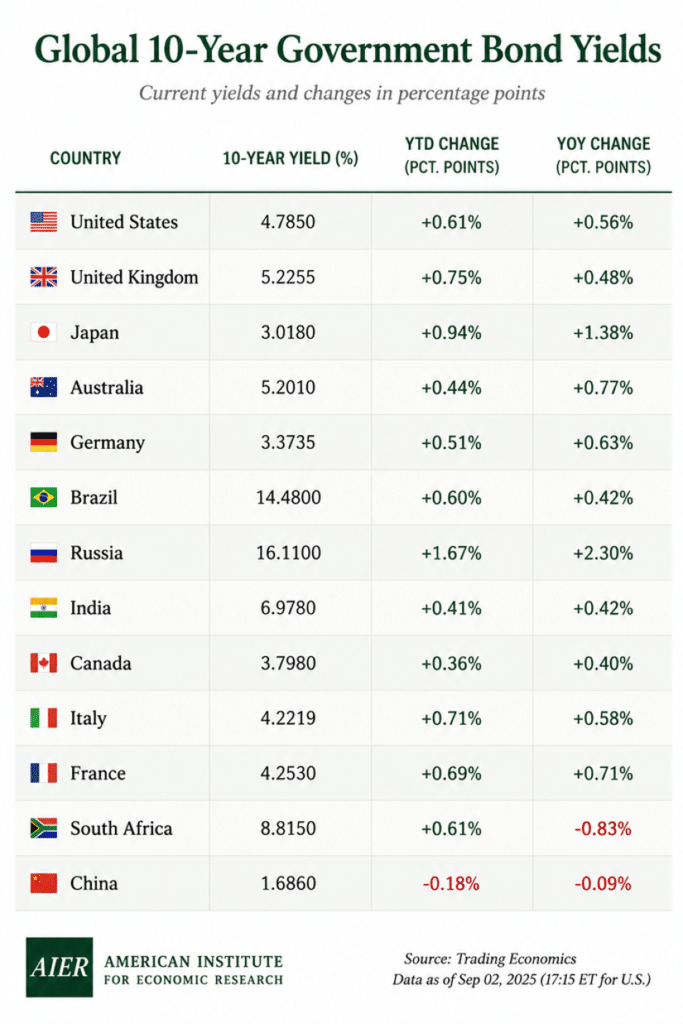
Oil prices and renewed inflation worries are part of the explanation, as is the growing possibility that central banks will have to keep monetary policy restrictive for longer than markets have expected. But these are proximate causes. The bigger story began several years ago. Governments entered the covid period already heavily indebted, then responded to the pandemic with enormous fiscal programmes supported by extraordinarily easy monetary policy. Central banks subsequently discovered that the resulting inflation was neither especially transitory nor easy to eradicate. Now, the consequently larger debts have to be financed and refinanced in markets where investors once again demand compensation for inflation, duration and fiscal risk.
For the United States, the arithmetic becomes daunting fairly quickly. Gross federal debt recently passed $40 trillion, with roughly $32.3 trillion held by the public. The weighted-average maturity of marketable Treasury debt is about 71 months, although roughly one-third matures within the next year. So, a 20-basis-point increase in the 10-year Treasury does not suddenly reprice $32 trillion of debt. But the government does not get to ignore higher rates, either. Something on the order of $10 trillion of marketable debt must roll over within a year. Meanwhile, Washington continues to borrow hundreds of billions more to finance new deficits.
A household analogy is useful here, with one qualification. Imagine an enormous mortgage that resets in pieces rather than all at once. A homeowner with a fixed-rate mortgage does not care very much if mortgage rates jump tomorrow: he cares about when he has to refinance. The US Treasury is constantly refinancing: some portion of the federal government’s enormous mortgage matures every day.
We can already see that process in the numbers. The average interest rate on interest-bearing Treasury debt was about 3.32 per cent in January. By July it was roughly 3.45 per cent. Thirteen basis points sounds like market noise, until the principal involved is measured in tens of trillions of dollars.
Using $32.3 trillion of publicly held debt as a rough base, every sustained 5-basis-point increase in the government’s average financing cost eventually means about $16 billion more in annual interest expense. Ten basis points means roughly $32 billion; 25 basis points, $81 billion; 50 basis points, $161 billion. A full percentage point works out to approximately $323 billion per year – about what the US spends on veterans’ support. Those are steady-state figures, not next-year budget estimates, because the existing debt has to reprice first. If roughly one-third of the debt rolls over within twelve months, a 10-basis-point increase would initially add something closer to $10–11 billion to the annual cost of the existing debt, before considering new borrowing.
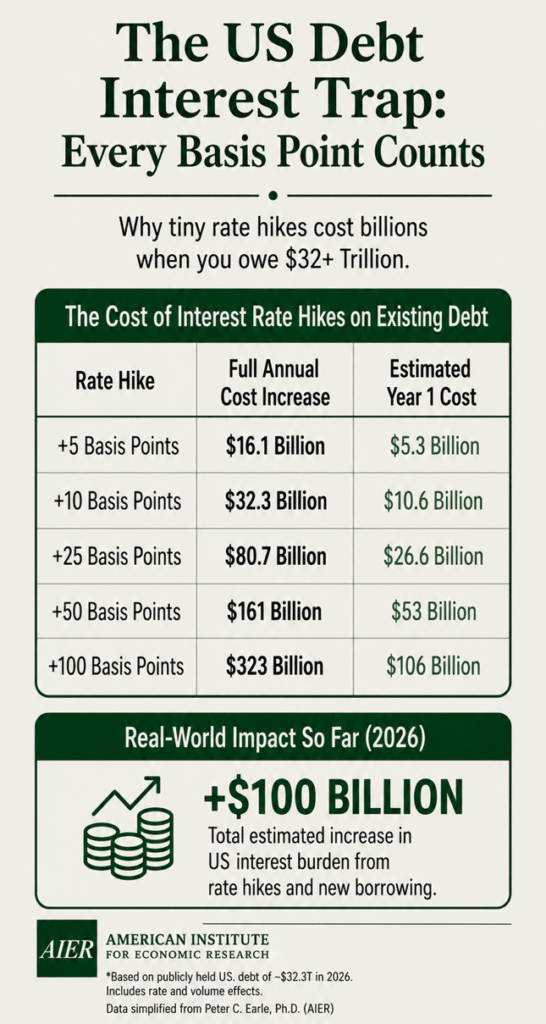
The change since January gives some idea of the scale involved. If the 13-basis-point increase in the US Treasury’s average interest rate were eventually reflected across today’s publicly held debt, the annualised increase would be around $42 billion. But the interest rate is only half of the problem: publicly held US Treasury debt has itself grown by roughly $2 trillion. Financing that additional principal at around 3.5 per cent adds another $65–70 billion annually. Put the two together, and the increase in the annualised interest burden is plausibly already in the neighbourhood of $100 billion. That is a run-rate calculation, not a claim about actual fiscal-year outlays, but it illustrates what happens when both the amount borrowed and the price of borrowing rise together.
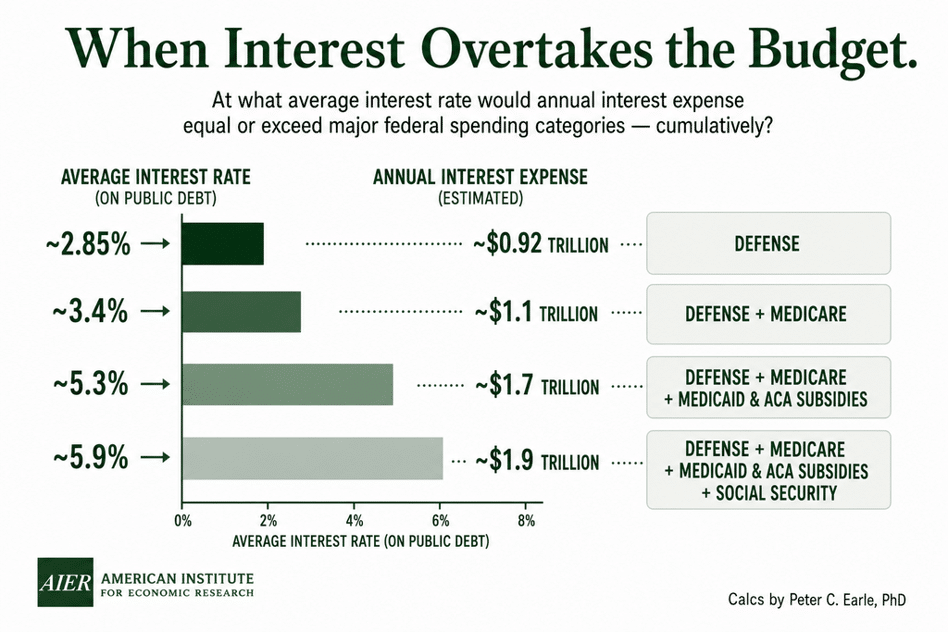
The budget implications are no longer theoretical. The US Congressional Budget Office (“CBO”) projects net federal interest expense above $1 trillion in fiscal 2026, against roughly $898 billion of defence spending. In other words, interest has already become larger than the defence budget. Medicare is roughly $1.1 trillion and Social Security around $1.7 trillion, with Medicaid and ACA subsidies representing another substantial expenditure.
There is another way to visualise the problem. Using the same $32.3 trillion debt base and deliberately simplified arithmetic, an average financing cost of around 2.85 per cent produces an interest bill roughly comparable with defence spending. Raise the effective financing cost and the interest burden becomes comparable with progressively larger combinations of defence, Medicare, Medicaid and ACA subsidies, and eventually Social Security. This is an illustration, not a forecast: Treasury debt matures at different times, inflation-linked securities complicate the calculation, the government receives some interest income and the debt stock will not remain at $32.3 trillion. But none of those qualifications changes the basic point: with this much debt outstanding, surprisingly small movements in average financing costs translate into very large amounts of money.
That is what makes the present bond selloff, and consequent rise in yields, significant. For years, developed-world governments operated as though enormous debt stocks and negligible financing costs could coexist more or less indefinitely. Covid pushed that experiment much further. And with the return of persistent inflation, the price of money changed.
Bond markets are now forcing governments to confront the change in circumstances. Yesterday’s deficit does not disappear when the fiscal year ends; it becomes part of the debt that has to be serviced tomorrow. Rising yields therefore work much like higher mortgage or credit card rates, except that governments are refinancing obligations measured in trillions. As more debt rolls over, the consequences migrate from trading screens into national budgets. Money spent servicing the debt is money that cannot be spent on defence, infrastructure, health care or Social Security without some combination of raising taxes, borrowing still more, or engaging in financial parlour tricks. At some point, the bond market stops offering commentary on fiscal policy choices and starts imposing limits. We appear to be approaching, if not at the early stages, of that phase.
About the Author
Peter C. Earle, PhD, is Senior Director of Research at the American Institute for Economic Research (“AIER”). He is an economist and financial market practitioner with over 30 years of experience in financial markets, macroeconomics and economic analysis.
Dr. Earle has written and edited eight books and authored hundreds of articles, op eds and research papers. He serves on the Editorial Board of Financial History (the quarterly journal of the Museum of American Finance), the Advisory Board of the Institute for Liberty and Economic Education (“ILEE”) and as an Associated Scholar of the Mises Institute. He is also the Managing Partner of Shadow Gamma, LLC. His work and commentary have been featured in The Wall Street Journal, Financial Times, Barron’s, Bloomberg, Reuters, CNBC, Grant’s Interest Rate Observer, NPR and numerous other media outlets and publications.
The Expose Urgently Needs Your Help…
Can you please help to keep the lights on with The Expose’s honest, reliable, powerful and truthful journalism?
Your Government & Big Tech organisations
try to silence & shut down The Expose.
So we need your help to ensure
we can continue to bring you the
facts the mainstream refuses to.
The government does not fund us
to publish lies and propaganda on their
behalf like the Mainstream Media.
Instead, we rely solely on your support. So
please support us in our efforts to bring
you honest, reliable, investigative journalism
today. It’s secure, quick and easy.
Please choose your preferred method below to show your support.

Categories: Breaking News, Latest News, US News, World News
THIS IS ALWAYS THE PLAN BY DESIGN…
If we think we all have the power to choose or given a choice, that’s was an illusion. We never had a free will from birth.
We (people with souls) tried to stop the lies & deceptions of the ‘selected’ government. however too many sheeples outnumbered the real human causing the DEMO-CRAZY plan wins.
Until all the useless sheeples are gone, the grand design plans of controlling the lives of human as pleases will always executed with flying colours.
The world full of stupid karens.
BTW, I’m tired of these self-righteous environmentalists of climate diaper-change morons. These white bourgeois liberals who think the only thing wrong with this country is there aren’t enough bicycle path for people trying to make the world safe for their Volvos & Mercedes.
I don’t ever remember being asked if I wanted to be “governed”. More to the point, I don’t ever remember any “government asking me if if I wanted to be “governed”. Nuff said.
If you’re able to access an internet, you’re already ‘governed & bounded’ by the rules & regulations of ‘selected’ human laws no matter you like it or not. There are no escape from it.
Unless you lived in a cave somewhere deep in forest of amazon, then you’re not ‘govern’ by government. The only law you’re required to follows is the law of the jungle (TarZan = dark black goo = crude oil).
Saying NOT REMEMBERED to be governed is a lie. Denials syndrome is a real viral disease these days affected all stupid karens.
I pretty sure that you are not aware about our government DOES NOT CARE if you have foods on your table each day. How many bills need to be paid to survive throughout the months.
Those who govern you only cares about how many MORE TAX they could squeeze out from all of business class of economic-slave-humans. We lived to give MORE money to the ‘government’ living a luxurious lifestyle without paying a single tax or spending a single dime to help the poor.
Just give us a favor or give us a break & keep on sleeping. please..!!!
WE are Born into an old school masonic system which is a war platform governed by admiral law under lucifer and we are unwittingly captured in to it from birth and are a debt slave our birth certificate is a corporate contract that creates a straw man we are seen as a dead soul or a vessel lost at sea which can be raped and pillaged and your social security number is a bank account number they trade on. They print Fiat money and lend it to the corrupt government and they tax us on our labour. That money made from our labour and energy is real money we are giving to to them in taxes which they use for usury in short they create fake money that does not exist they tax us the crown collects the money then they charge huge interest on our own money. Total Theft. Currently the British Empire is being dismantled and a new QFS banking system is replacing SWIFT to stop corrupt bankers stealing our money and causing wars for control and sacrifice to their God. There is a war between good and evil and we all have to choose a side I choose God and Good and we must unite stand up to these evil people and there very evil agenda.
Think you have mis-interpreted my comment, I wasn’t disagreeing with you.
Voluntaryist scholar Robert Higgs: “The beginning of political wisdom is the realisation that despite everything you have always been taught, the government is not really on your side; indeed, it is out to get you. The mass belief in the general beneficence of democracy represents a kind of Stockholm syndrome writ large. We shall never have real, lasting peace so long as we give our allegiance to the whole conglomeration of institutionalised exploiters and murderers we know as the state.”
Perhaps you will know where I’m coming from now?
Is Glastian from the Armenian Galstyn?
No, a bit closer to home in the UK, but thanks for asking. You’re knowledge of Armenian family is praiseworthy though!
From the inception of the Crown 1694 it was created for the act of fraud. Designed theft ( taxation) from the people via so-called democracy.
Well said about tax fraud via democracy (demo-crazy). Congrats.
So, nothing new!
The only entity in Debt Slavery is that owning all debt; the City of London Central Bank Family Mafia and the BIS in Basel, Switzerland.
THEY OWN ALL CURRENCIES; and every unit is DEBT TO THIS SLAVE MASTER MURDEROUS CREW.
City of London’s Central Bank Family Mafia are Luciferian and Pagan Demon Worshiping Pedophiles, Cannibals and Vampires.
THEY MUST BE ERADICATED.
Manufactured Folic acid used in flour and many other products, will not allow natural folate (B9) to cross the blood brain barrier, where it is very essential to the brains housekeeping cleaning functions. Folic acid can occupy folate receptor alpha (FR) gatekeepers on the blood-brain barrier… thus blocking natural 5-MTHF folate from entering, which is necessary for the brains cognitive functions. It is thought to be very useful, but can cause very negative results, and should not be so widely used as it is.